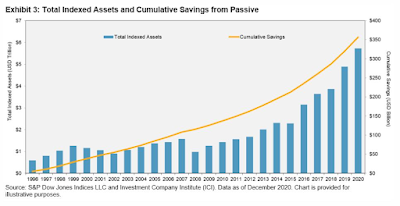
~ Kevin Duffy, "Fade to Black," The Coffee Can Portfolio, p. 10, October 22, 2024
Showing posts with label passive investing. Show all posts
Oct 25, 2024
Kevin Duffy on the passive bubble
Over [the past 10 years], a staggering $6.0 trillion has poured into passively managed funds, with $2.3 trillion pulled from active funds.
Jul 10, 2024
Whitney Tilson on holding on to winning stocks
Almost no human being has the ability to do this. If you want to know the main reason index funds outperform almost all active managers over a long period of time, it's because they never sell their winners. They let their winners run. Just look at the S&P 500 index. The S&P 500 index has never sold a share of Apple, Nvidia, Microsoft, Berkshire Hathaway, Visa, Mastercard, Lilly. I just named almost all the top 10 stocks in the S&P that drive its entire return.
~ Whitney Tilson, "Be Greedy and Let Your High-Quality Winners Run," Stansberry Investor Hour, 26:35 mark, July 8, 2024
Feb 21, 2023
Joel Tillinghast: avoid investing in the single largest stock in the S&P 500
Familiarity can work against investors. If you continuously invested in the single largest S&P 500 stock by market value between 1972 and 2016, your compound returns would have been less than 4 percent, while the index earned over 10 percent. A smiliar but smaller effect was seen with the ten largest S&P 500 stocks.
~ Joel Tillinghast, Big Money Thinks Small, p. 60
Jan 5, 2023
Horizon Kinetics: indexation and asset allocation models are broken
Investors now face questions they haven’t had to consider for decades. Until this past year, the entrenched basketof-securities approach to investing meant one didn’t have to think, one just bought the recommended asset classes. That approach is now in disarray. It depended on a simplistic presumption that the prior 20 or 40 years of daily price data represented normality. It couldn’t contemplate a change in those presumptions. History is a lot messier. That data, it turns out, described an anomalous period, not a normative one.
It should now be clear that indexation and asset allocation models – at least as practiced – can no longer be relied upon as having predictive value. Bonds, for instance. Over the past 20 years, after taxes, they returned only about 2%, annualized. Even accepting the government’s CPI calculation that inflation averaged only 2.5%, that means bonds had a negative real return, a two-decade loss of purchasing power. That was not supposed to happen (on the reasoning that it hadn’t happened before). And that was during a period of relatively benign inflation. ‘Benign’ is not the likely caption for the next 20 years. Rationally, one must rethink one’s approach to bond investing. One must rethink other presumptions about the standardized approach to investing.
~ Horizon Kinetics 2023 investor letter, January 4, 2023
Dec 27, 2020
Mike Green on how passive investing is distorting capital allocation
That is actually a very important role: taking money from bad companies and giving it to good companies is a critical role in the capitalist system, effectively allowing those who are efficient and intelligent allocators of capital, to give money to management teams that have good prospects in terms of generating future wealth. What we've created now is a distortion that's a funhouse mirror effect, right? Where we've presumed everyone is doing this for us where it is a fool's game to do it for ourselves.
~ Mike Green, "Why The Rise of Passive Investing Might Be Distorting The Market," Odd Lots podcast with Joe Weisenthal and Tracy Alloway, January 23, 2020
Jul 17, 2020
Mark Urquhart on passive investing
The notion that equity indexes are somehow risk-free states has to my mind always been a dangerous fallacy which has been amplified by the rise of passive investing.
Actually, all three of the significant market crises which my career has contained — technology, media and telecoms (TMT), the financial crisis and now the coronavirus — have been linked by so much damage being done to particular parts of the index that it demolishes the thesis that index investing can diversify away such risk.
~ Mark Urquhart, money manager at Baillie Gifford in Edinburgh, Scotland, "Opinion: The hidden risk in your S&P 500 index fund," MarketWatch.com, July 17, 2020
Labels:
diversification,
passive bubble,
passive investing
Feb 22, 2020
Kevin Duffy on the passive bubble vs. active anti-bubble
Besides bonds, there is plenty of herding into private investments by the wealthy, especially venture capital and private equity. Away from the top 1%, the obvious crowding is into passive investing. After a decade when U.S. large cap stocks outperformed most active managers, the typical investor is pouring money into funds that mimic an index, like the S&P 500, that charge very little in fees.
While I applaud being frugal and holding active managers’ feet to the fire, the crowd is very likely looking in the rearview mirror at this point. In general, stocks in the S&P 500 have become quite expensive while many across the “index divide” are actually fairly cheap. The latter area is where we need to hunt for bargains.
~ Kevin Duffy, The Coffee Can Portfolio, February 18, 2020
While I applaud being frugal and holding active managers’ feet to the fire, the crowd is very likely looking in the rearview mirror at this point. In general, stocks in the S&P 500 have become quite expensive while many across the “index divide” are actually fairly cheap. The latter area is where we need to hunt for bargains.
~ Kevin Duffy, The Coffee Can Portfolio, February 18, 2020
Jan 15, 2020
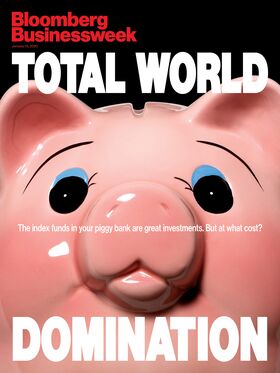
Bloomberg Businessweek on index funds
The index fund is one of a handful of unambiguously beneficial financial innovations. Before it caught on, investors routinely paid sky-high fees to active stockpickers who often delivered subpar returns. The near-universal popularity of index funds puts them up there with Social Security, Stevie Wonder, and streaming TV.
~ Bloomberg Businessweek, "The Great Index Fund Takeover," January 13, 2020
Labels:
indexation,
magazine covers,
passive bubble,
passive investing
Jun 11, 2019
Lance Roberts on passive investing
The one thing about passive investing that makes me chuckle a bit is that passive investing is fine until the selling starts and then everybody becomes active sellers.
~ Lance Roberts, June 3, 2019, The Lance Roberts Show, 6:00 mark
Nov 26, 2018
Michael Santoli on $6.6 bil flowing into Fidelity's zero fee index funds (excluding ETFs)
Low-fee exposure to the equity market is the new performance chasing.
~ Michael Santoli, as appeared on CNBC, November 26, 2018
Labels:
indexation,
mutual fund flows,
passive investing
Nov 19, 2018
Jim Grant on passive investing
By definition, an index investor must be agnostic as to price and value – he takes the market for what it is, and what it appears to be (or has appeared to be). A persistently rising market is a
money machine.
~ Jim Grant, Grant’s Interest Rate Observer, November 2, 2018
Apr 11, 2017
Kevin Duffy on the Fiduciary Rule
If we’re going to pass a law against conflicts of interest,
shouldn’t there be a law against lobbying the government when such a conflict
exists? (Which is always, of course.) How can John Bogle not admit
that he and his friends benefit from the Fiduciary Rule?
The irony, of course, is that indexation needs discovery
agents, and this legislation will put more obstacles in their path.
Without price discovery (e.g., interest rates set by the market) and discovery
agents (active investors, short sellers, upstart entrepreneurs), there is no
vibrant economy that generates the returns Mr. Bogle’s customers covet.
It can’t be a coincidence that the government only recently
discovered the merits of high-liquidity low-fee investing after a tripling of
the S&P 500 in 8 years and a 35 year bull market in bonds. Should we
be thanking them for ringing the bell yet again?
~ Kevin Duffy, April 11, 2017
Subscribe to:
Posts (Atom)