Showing posts with label insurance. Show all posts

Dec 25, 2025

Grant's on how life insurers are tied to the AI boom

Private equity and debt funds are big investors in data centers that power AI chatbots.  A bust in the AI boom would surely add to pressures mounting from the slow-moving p.e. default wave.  And as the knee bone is connected to the thigh bone, so life insurers are fused to private funds (both as investors in them and as financiers of them).  Annuitants and policy holders may soon be reminded of these facts of life and high finance.

[...]

As it is, U.S. life insurers have committed roughly one-third of their assets to private credit.  And owing to widespread private equity ownership, life insurers are themselves highly leveraged, with 22 out of the top 80 carriers by asset size reporting liability-to-surplus ratios of over 30 times as of year-end 2024.

[...]

Another thing: American life insurance held $1.3 trillion in notional exposure to interest rate derivatives at year-end 2024.  "As fixed-rate receivers," the BIS reminds its readers, "insurers typically face margin calls in periods of rising rates."

And another: Many annuitants have the right to redeem early, with surrender penalties of 10% or less.  Annuity holders are most likely to accept that penalty when they can get higher rates of return elsewhere, that is, when rates are rising.

~ "Tomorrow's news today," Grant's Interest Rate Observer, December 5, 2025

for Insurers Managing $13 Trillion ... 

Jan 15, 2025

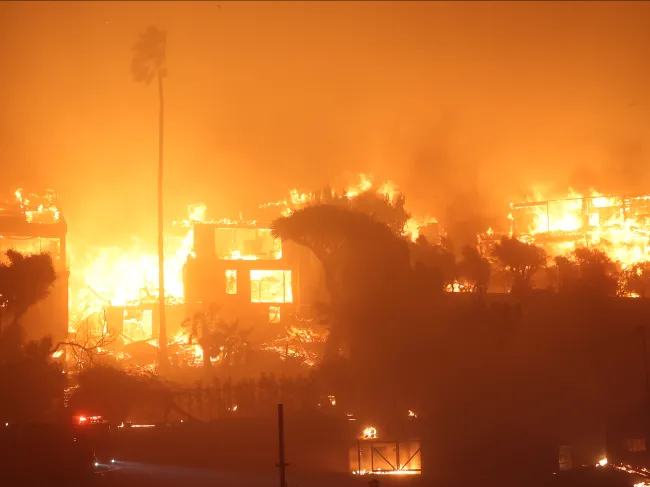
Connor O'Keeffe on why many victims of LA wildfires were uninsured

Making matters worse, many of the homes destroyed last week were uninsured.  Progressives and establishment media outlets seized on this fact to blame climate change for driving insurance providers out of high-risk areas. 

This talking point is complete nonsense.  If the risk of natural disasters in an area people want to live in increases, that’s good for insurance companies.  It drives up the demand for their product.  It’s true that home insurance providers have been fleeing the areas affected by these fires—with one provider canceling thousands of policies in the Pacific Palisades in the last year alone.  But that’s not because of climate change, it’s because of government intervention.

[...]

When governments mess with insurance prices—either through subsidies, cheap public insurance, or price controls—the result is always the same. More people move to dangerous areas that are highly susceptible to natural disasters. 

In 1988, California passed a law that forced insurance prices down by 20 percent, banned providers from using forecasts of future risk to set prices, and subjected all future price increases to government oversight. With rates severely decoupled from risk, the state saw extensive development in some very fire-prone areas. Then, after an exceptionally bad fire year in 2017, insurance providers tried to get approval to raise premiums to account for the high level of risk across the state. The government said no. 

As a result, seven of the twelve largest home insurance providers pulled out of California. And that trend is continuing today. 

~ Connor O'Keeffe, "Climate Change Is Not the Cause of California’s 'Insurance Crisis'," Mises Wire, January 14, 2025